Enterprise
First Time Shipping Fragile Goods? Who Carries the Loss When a Box Arrives Broken
Declared value, third-party coverage, self-insuring and 3PL packing compared, and how the same decision has shifted over the past decade for a first-time shipper.
EnterpriseBram Voskuijlen
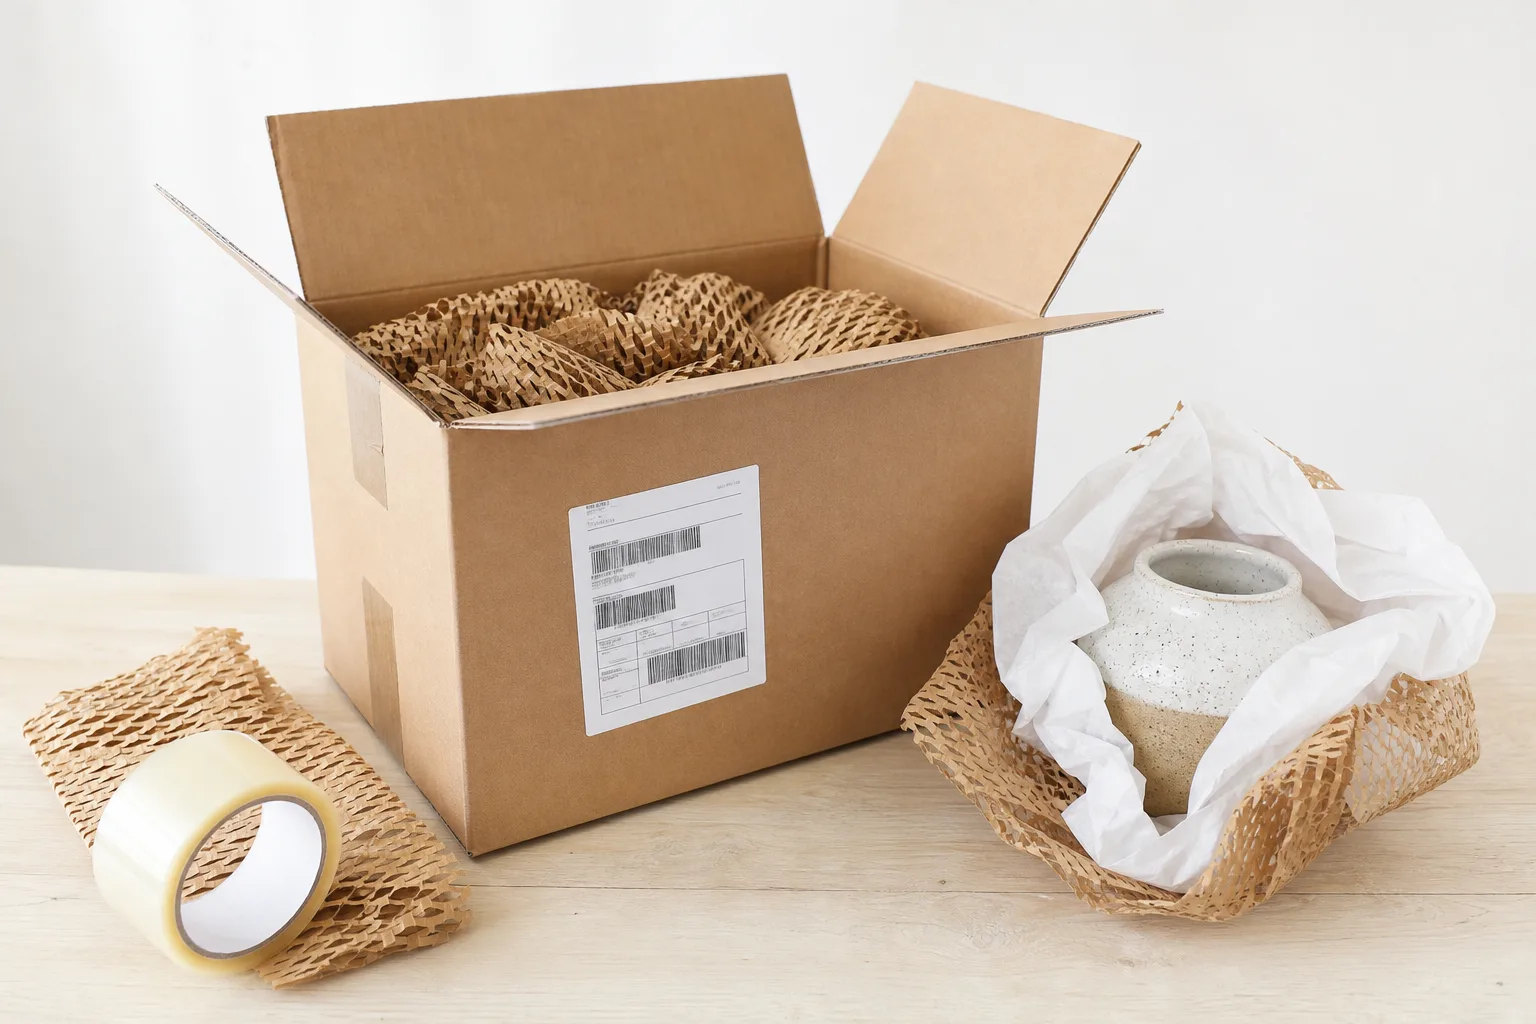
The first time you ship something breakable to a stranger, the question you are actually answering is not how much bubble wrap to buy. It is who pays when the box arrives crushed, and whether that person is you, the carrier, a separate insurer, or a fulfillment company whose contract you signed without reading the liability section. A decade ago that question had three practical answers and a fair amount of slack in the system. It now has more answers, tighter rules, and far less slack. The money involved is small per package and large per year.
The default answer, and why it is smaller than people expect
Every major parcel carrier includes a baseline liability figure in its tariff, usually a modest per-package amount, and sells additional coverage above it by declared value. First-time shippers consistently read declared value as insurance. It is not. It is a contractual cap on what the carrier will pay if the carrier is found at fault, and fault is where the argument happens. Ten years ago the practical experience of filing a declared value claim on a modestly priced item was that it often paid without much scrutiny, because the cost of investigating a small claim exceeded the claim. That is no longer reliably true. Claims now run through systems that compare the damage photographs against the carrier's published packaging requirements, and a claim denied for insufficient packaging is a normal outcome rather than an unusual one.
The shift matters most for the person shipping their first few hundred packages, because the packaging requirements are specific in a way nobody reads until a claim is refused. Two inches of cushioning on all six sides of a fragile item, double-wall corrugated for certain weights, inner and outer boxes for glass, no reused cartons with old labels still attached. Those lines existed ten years ago. What changed is that they are now enforced at the point of claim rather than treated as advice. A first-timer who packs well and photographs the packed box before sealing it is in a materially different position from one who does not, and the difference only shows up once.
Third-party coverage, which grew up in the gap
Alongside carrier declared value there is now a mature market in third-party parcel coverage, sold either as a standalone policy or bolted into the shipping software most small sellers already use. Ten years ago this was a specialist product that a first-time shipper would never encounter unless someone told them it existed. Today it is frequently a checkbox inside the label-buying screen, priced per package as a percentage of declared value, and usually cheaper than the carrier's own declared value charge at the same coverage level. The claims process is separate from the carrier's, runs on its own evidence standards, and in many cases pays faster because the insurer's incentive is renewal rather than deflection.
The trade-off is that you are now dealing with two counterparties instead of one, and the policy will have its own exclusion list. Common exclusions include certain categories outright, items shipped without signature above a value threshold, and loss claims filed before a waiting period has run. None of this is hidden, but a first-time shipper comparing the checkbox price against the carrier's number is comparing prices and not terms. Read the exclusion page once, at the start, before you have a damaged item and a customer waiting. It takes twenty minutes and it decides what the coverage is actually worth.
Self-insuring, which is what most small shippers quietly do
The guidance assumes shippers insure. In practice a great many small operations buy no coverage at all, absorb the occasional breakage as a cost of sales, and reship or refund without filing anything. This is a legitimate strategy and sometimes the correct one, because coverage priced at a few percent of declared value on every package will, over a year, exceed the cost of the handful that break, provided your damage rate is genuinely low and your average order value is genuinely small. The arithmetic turns against you quickly at higher values. One $900 item lost without coverage wipes out a year of premiums you did not pay.
What changed in a decade is the ability to know your own damage rate. Ten years ago a first-time shipper self-insured on instinct. Now the order data exists, the refund reason codes exist, and anyone with a spreadsheet can calculate breakage as a percentage of units shipped after three months of trading. Self-insuring with a measured number behind it is a decision. Self-insuring because you never priced the alternative is a drift. The practical approach most experienced small shippers land on is a value threshold: nothing under a set dollar amount gets coverage, everything over it does, and the threshold is reviewed when the damage rate moves.
Handing packing to a 3PL, and where liability lands then
Outsourcing fulfillment moves the packing decision to someone else and moves the liability question with it, though rarely as far as first-time clients assume. A third-party logistics contract will typically limit the provider's liability to a fixed amount per unit or per shipment, often tied to a schedule rather than to your product's actual value, and will carve out damage occurring in transit after the parcel leaves the warehouse. The provider is responsible for packing to the agreed specification. If the specification is thin, and you approved it, the loss comes back to you. Ask for the packing spec in writing and the liability clause in the same conversation.
The decade's real change here is accessibility. Fulfillment at small volumes was largely unavailable ten years ago, and a first-time seller shipping fifty units a month packed them at the kitchen table. That option is now open at much lower volumes, which means a genuine comparison exists where previously there was none: your own packing with your own coverage, against a provider's packing with a contractual cap. Separately, the Federal Trade Commission oversees the rules governing mail and internet merchandise orders, including the obligations a seller carries toward the buyer on shipment timing and refunds, and those obligations do not transfer to a logistics provider no matter what the contract says. The customer's counterparty remains you.
The cleanest way through all of this for a first shipment is to settle three things before the first label prints: what a single item is worth to replace, what your packing actually looks like against the carrier's published standard, and which of the four routes you are using on purpose. Write the answers down. The decision gets much easier the second time, and by the hundredth it is a threshold in a spreadsheet rather than a question at all.