Property
Hail Claim Handed to a Traveling Adjuster? How to Work a File That Changes Hands
A hail claim handled by a deployed catastrophe adjuster runs on a scope, a software estimate and a reinspection, and knowing which steps are reversible is most of the work.
PropertyCecelia Hartnoll
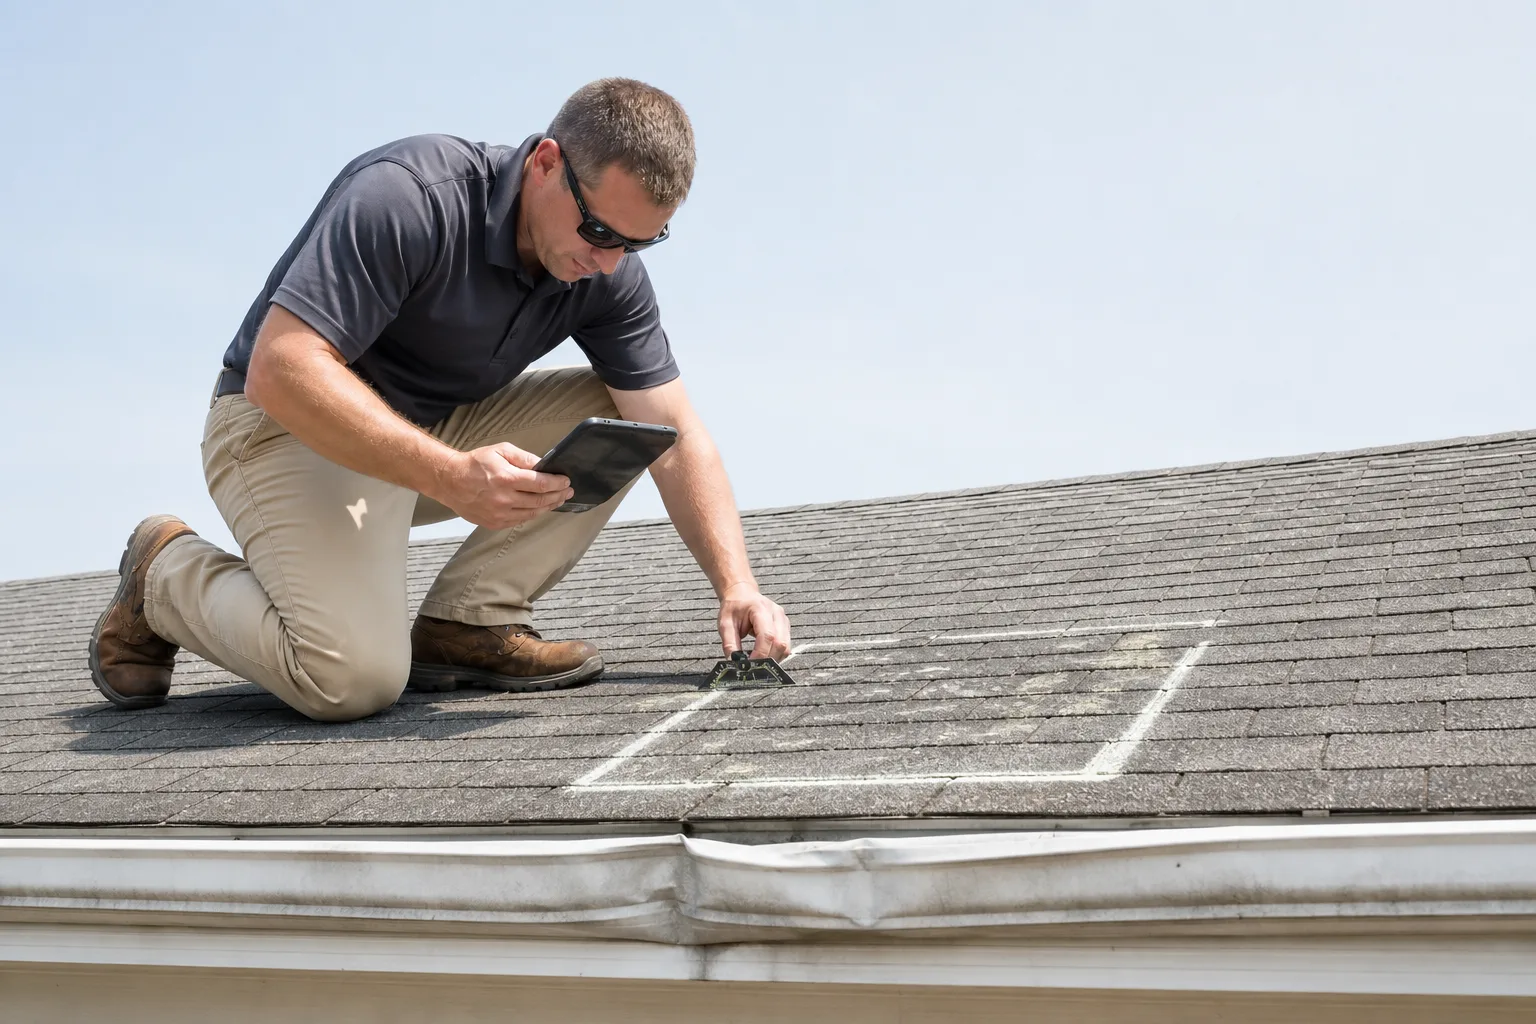
A hailstorm crosses three counties on a Tuesday afternoon, and by Friday the insurer that covers your house has more open claims in that zip code than it has employees within two hundred miles. The person who climbs your roof the following week is almost certainly not a staff adjuster from the regional office. She is an independent adjuster under contract, deployed for the event, carrying a tablet, a pitch gauge and a caseload measured in the dozens. Understanding why that is the normal arrangement, rather than an insult to your file, changes how you handle the next six weeks.
How adjusting stopped being a local job
For much of the twentieth century, property claims were worked by salaried adjusters who lived in the territory they covered, knew the contractors, and wrote estimates in longhand from unit prices they carried in their heads. That model handled routine losses well and catastrophes badly, because a single wind event could generate a year of ordinary claim volume in a week. Insurers responded by building a surge layer: independent adjusting firms that maintain rosters of licensed adjusters available on deployment, paid per file or per day, mobilized when a storm crosses a threshold. The capacity problem was solved. The continuity problem was created.
Two other changes locked the current shape in place. Estimating software became the common language of the industry, so that a scope written on a roof in Texas produces line items and prices that a desk examiner in another state can read, question and approve without ever seeing the house. State insurance departments, meanwhile, built licensing and continuing education requirements for adjusters, including the public adjusters that homeowners hire on their own behalf. The result is a process that is more consistent in its arithmetic and less continuous in its people. Your file will be competent. It will also travel.
One narrow case: a twenty-two-year-old asphalt roof, moderate hail
Take a specific loss, because the general advice is useless without one. Three-tab asphalt shingles installed in the early 2000s, a storm with reported one-inch stones, bruising visible on the south and west slopes, two dented gutter aprons, a screen torn on a rear window. No water has come inside. This is the most common hail claim in the country and the one where outcomes diverge most, because nothing about it is dramatic enough to be obvious. The adjuster will chalk test squares on each slope, count hits within a ten by ten foot area, photograph the mat where granules have been displaced, and note the age and layer count of the covering.
What she records in that hour determines almost everything afterward. If the hit count on two slopes meets the threshold her employer uses and the other two do not, the estimate may come back as repair of two slopes rather than replacement of the roof, which is where your own documentation starts to matter. Photographs of the gutters, the soft metal on vents and the window screen establish that stones of a certain size actually fell on your property, which is the same evidence the desk examiner will later use to decide whether the bruising is storm damage or ordinary aging. Pull the original roofing invoice if you have it. Age is a coverage fact, not an opinion.
The visit, the estimate and the reinspection
Be on the property, and be useful rather than watchful. Walk the perimeter first and point out what you have found, including anything you cannot see from the ground, because the adjuster's scope is built from what she observes and what you direct her to. Ask three things before she leaves: which slopes she is scoping, whether your policy pays replacement cost or actual cash value on the roof specifically, and who to contact when a contractor finds something her estimate does not cover. Write down her license number and the adjusting firm's name, not just her cell phone. She may be gone from the state within two weeks.
The estimate that arrives is a starting scope, not a final offer, and the mechanism for changing it is the supplement. When your roofer opens the deck and finds rotted sheathing, or the local code requires ice and water shield that the original roof never had, those items go back to the insurer as a documented supplement with photographs and the code citation attached. This is routine. It is also where the handoff bites, because the adjuster who saw your roof is now three states away and a desk examiner is reading her notes. If the disagreement is substantive, ask for a reinspection by a local adjuster. That request is normal, it is usually granted, and it costs you nothing but time.
Which steps you can undo, and which you cannot
Five years from now, three decisions from this claim will still be visible. The first is the release. Signing a final release or a settlement agreement closes the file, and reopening it afterward requires proving something you could not have known, which is a much harder standard than simply finding more damage next spring. Hold the release until your contractor has opened the roof. The second is the choice between repairing two slopes and replacing the covering, because a partial repair on a twenty-two-year-old roof leaves you with mismatched material, a shorter remaining life and a documented prior hail claim, all of which surface at resale and at renewal.
The third is the deductible arithmetic on small losses. A claim reported and closed for slightly more than the deductible still appears in your loss history, and on a wind and hail deductible expressed as a percentage of the dwelling limit, the recoverable amount may be smaller than you assume. That calculation is reversible only before you report. What remains reversible throughout is almost everything procedural: you can request a reinspection, submit a supplement, ask for the estimate line by line, engage a licensed public adjuster on a contingency basis, or escalate to your state insurance department. Federal involvement in property coverage is narrow, and FEMA is responsible for the flood program rather than wind and hail, so state regulators are the ones who oversee this conduct.
The deployment model that sends a stranger to your roof also sends someone who has scoped four hundred hail losses that month. Treat her as a technician working a documented process, keep your own file in parallel, and hold the two irreversible signatures until the deck is open and the scope is honest.